Best Savings Accounts to Open in Nigeria Right Now
If you want a savings account in Nigeria right now, the best choice depends less on the biggest headline rate and more on what you need the money for: emergency access, a named goal, a strict lock, a bank-style account, a starter account or a non-interest structure.
Methodology disclosure
Methodology: How we rank the best savings accounts
Picking a savings account in Nigeria is harder than it should be. One product promises a high headline return but does not fully explain who gets the top rate. Another keeps your money flexible, but quietly punishes heavy withdrawals by cancelling that month's interest. Another looks like a normal bank account, except the interest only holds if you stay under a withdrawal limit. If you just want somewhere safe and sensible to keep money, that mix can leave you comparing numbers that are not really comparable.
What separates the good options from the weak ones is not only the annual percentage on the page. You need to check how easy it is to get your cash back, whether "free" access still comes with an interest penalty, whether there is a meaningful minimum balance, and whether the account actually suits the job you want it to do. A strict fixed lock can be great for discipline and still be a terrible emergency fund. A flexible wallet can be excellent for short-term savings and still disappoint if you withdraw too often.
This ranking leans into that reality. Instead of pretending there is one perfect account for everyone, we ranked products by how well they fit distinct real-life uses: emergency savings, named goals like rent or school fees, high-discipline fixed saving, full-service bank saving, entry-level saving and non-interest saving. By the time you finish this list, you should know not just which products look strongest on paper, but which trade-offs you are actually agreeing to before you move your money.
Key takeaways
- Best overall for most people: Flex Naira by PiggyVest because it combines a clearly published 12% p.a. with real day-to-day access, though too many withdrawals can wipe out that month's interest.
- Best for planned goals: FairTarget by FairMoney stands out for up to 20% p.a., no minimum balance, flexible access and multiple concurrent goals, but the cited page does not spell out exactly what qualifies a saver for the top rate.
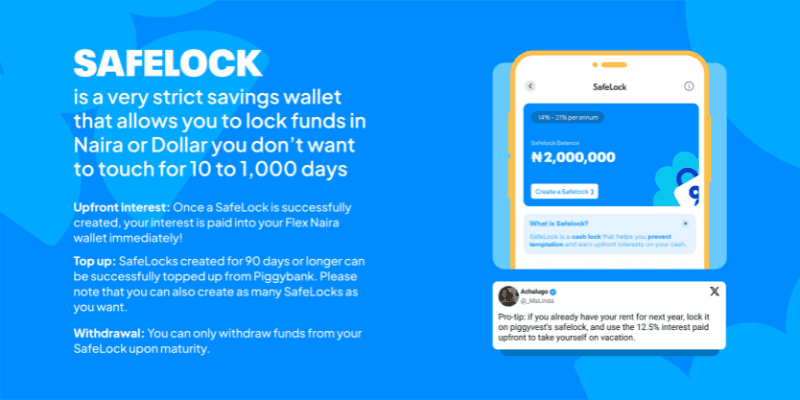
- Best for maximum discipline: SafeLock by PiggyVest is the strongest lock-it-and-leave-it option, but you should know PiggyVest's own public pages conflict: one says up to 19.5% p.a., while the FAQ ladder goes as high as 21% for longer tenors.
- Best traditional bank option: Fidelity High Yield Savings Account offers the clearest bank-style rate table in this sample, topping out at 10.45% p.a., with monthly interest and regular account features.
- Best non-interest option: Jaiz Savings Account (Mudarabah) is the clearest Sharia-governed option in this research, but it does not publish a fixed return, so you are choosing governance structure over yield certainty.
Not all savings accounts are the same
In practice, Nigerian savers are no longer choosing from one simple bucket called "savings account." In this small but current sample, you are choosing between at least five different models: a goal-based savings plan, a flexible savings wallet, a hard lock product, a traditional bank savings account, an instant starter account and a non-interest Mudarabah account. That matters because the best product for rent due in six months is not automatically the best product for emergencies, everyday overflow cash or faith-based saving.
The published returns in this shortlist also show why context matters more than chasing the single biggest number. The sample ranges from 8.175% on GTInstant to 12% on Flex Naira, up to 20% on FairTarget, 7.95% to 10.45% on Fidelity's tiered bank account, and up to 19.5% or 21% on SafeLock depending on which official PiggyVest page you read. Jaiz does not advertise fixed interest at all; it uses profit-sharing under Mudarabah. So the real question is not "Which number is highest?" but "Which structure actually matches how you will save and withdraw?"
That is especially important because some of these products reward self-control and punish convenience. Flex Naira and Fidelity HYSA both keep your money accessible, yet both can deny you interest for a month if you exceed their withdrawal conditions. SafeLock offers the strongest discipline, but by design it reduces flexibility. FairTarget tries to sit in the middle by combining goal saving with flexible access, which is attractive, though the top-rate mechanics are less fully disclosed in the cited source than some readers may want.
1) Flex Naira by PiggyVest — best overall for most people
If you want one option here that balances yield, access and simplicity, Flex Naira is the easiest product to recommend first. PiggyVest's FAQ describes it as a flexible savings wallet paying 12% per annum, with free withdrawals to a bank account or Pocket account. On a simple annual basis, ₦500,000 kept there for a full year would imply about ₦60,000 in interest if you stay within the product's rules. That is not the highest headline number on this list, but it is one of the clearest flexible-account offers in the sample.
The catch is important, and you should not gloss over it. PiggyVest says you lose that month's accrued interest if you make more than 4 withdrawals to a bank account or more than 6 withdrawals to Pocket in that month. So the withdrawals may be described as free, but they are not consequence-free if you use the wallet too heavily. There is also a rhythm constraint: withdrawals can only be initiated once every 10 hours, withdrawals of ₦3 million and above take 3 working hours to process, and the minimum amount you can access is ₦2,000.
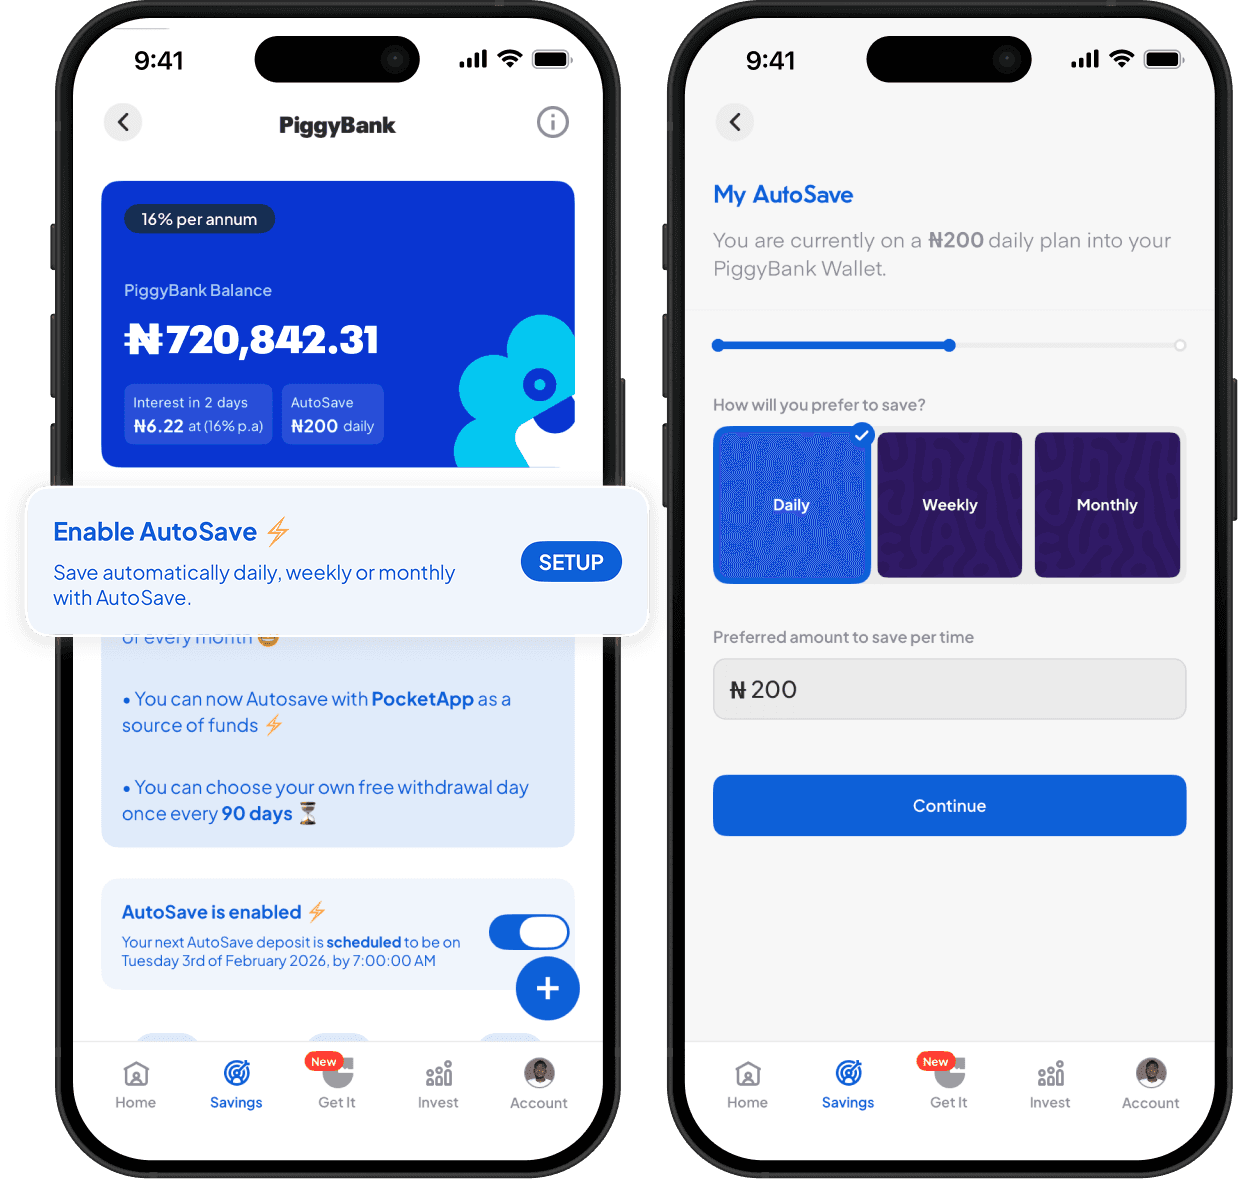
That combination makes Flex Naira strongest as an emergency fund or general-purpose savings hub, not as a spending account you dip into constantly. PiggyVest's extended features also help its case: the wallet can fund Piggybank, Target, SafeLock, Flex Dollar and Investify, and users can organise emergency funds with Labels. If your real need is "I want my money available, but I still want a respectable published return while I leave it alone," this is the cleanest all-rounder in the shortlist.
2) FairTarget by FairMoney — best for named goals
FairTarget earns its place because the feature mix is unusually strong for planned expenses. FairMoney markets it as a goal-based savings product for rent, school fees, travel, emergencies and other big expenses, with up to 20% p.a., no minimum balance, flexible access while saving, user-defined duration, automatic savings on your chosen schedule and the ability to create multiple goals at once. For somebody saving toward several separate targets, that is far more useful than a single undifferentiated savings bucket.
The appeal becomes obvious with a simple example. At the headline rate, ₦500,000 saved for a full year would amount to up to about ₦100,000 in return. But the phrase that matters there is "up to." In the cited page, FairMoney does not spell out in this research packet exactly which plan settings, tenors or conditions qualify a user for the maximum published rate. So while the upside looks strong, the rate disclosure is not as fully transparent here as PiggyVest Flex Naira's flat 12% or Fidelity's published rate table.
Still, FairTarget does a very good job of solving a common real-life problem: you want structure without a total lock. You can keep separate goals running, automate contributions and still retain flexible access while saving. The cited page's footer also states that FairMoney is licensed by the Central Bank of Nigeria, which helps on the trust side. If your savings life is organised around future bills rather than pure emergency liquidity, FairTarget is one of the most compelling products in this sample.
3) SafeLock by PiggyVest — best for disciplined fixed savings
SafeLock is for money you do not want to casually touch. PiggyVest describes it as a fixed savings option funded from Flex Naira or a debit card, with no access until maturity. The FAQ gives a detailed rate ladder: 14% p.a. for 10–30 days, 15% for 31–60 days, 16% for 61–90 days, 17% for 91–180 days, 18% for 181–270 days, 20% for 271–365 days, 20.5% above 1–2 years, and 21% above 2 years, all prorated for the chosen duration. The minimum amount per SafeLock is ₦1,000, and the maximum is ₦100 million.
But there is a disclosure issue you should know before treating 21% as settled fact. PiggyVest's public SafeLock landing page, reviewed the same day, presents a more conservative headline: lock funds for 10 to 1000 days and earn up to 19.5% interest per annum, paid upfront or at maturity. That means PiggyVest's own public materials are not fully aligned. Rather than quietly picking the higher number, the sensible reading is this: SafeLock clearly sits near the top of this sample for fixed-lock headline yield, but the exact top rate needs reconciling on the provider side.
Even with that caveat, the mechanics are still attractive for disciplined savers. If you locked ₦500,000 for a full year, the FAQ's 20% band would imply about ₦100,000 by maturity, while the landing page's 19.5% headline would imply about ₦97,500. If you chose a 90-day lock at the FAQ's 16% p.a. rate, the prorated return on ₦500,000 would be roughly ₦19,726 over that period. Those are meaningful numbers if your real goal is to remove temptation.
Unique feature spotlight: choosing interest upfront or at maturity
This is the most distinctive feature in the shortlist. PiggyVest says SafeLock lets you choose to receive interest upfront or at maturity, and it shows the exact interest rate and payout method before you confirm the lock. That is not standard across the other products here.
The choice changes the product's behaviour in a practical way. The FAQ says that if interest is taken at maturity, the lock can be broken after 90 days of creation, but breaking before maturity means you forfeit accrued interest. By contrast, upfront-interest locks stay closed until maturity. So the upfront option can feel attractive because you see value immediately, but it also commits you more tightly.
4) Fidelity High Yield Savings Account — best traditional bank savings account
If you want a savings account that still behaves like a bank account, Fidelity's High Yield Savings Account is the strongest fit in this sample. Fidelity says the account can be opened with any amount, requires a minimum operating balance of ₦5,000, and pays a tiered rate based on balance: 7.95% p.a. below ₦100,000; 8.45% from ₦100,000 to ₦4,999,999; 9.45% from ₦5 million to ₦49,999,999; and 10.45% from ₦50 million and above. That rate table is not flashy, but it is refreshingly explicit.
For a saver with ₦500,000, the relevant published rate is 8.45% p.a., which works out to about ₦42,250 over a full year if the balance stays in that band. Fidelity also says interest is paid monthly, which helps if you prefer regular crediting rather than waiting until the end of a long lock. The awkward part is the withdrawal condition: the account does not pay interest if you make more than 3 withdrawals in a month. So this is best used as a proper savings account, not as your daily transaction account.
What lifts Fidelity above some plain rate-table options is functionality. The product supports cheque and dividend warrant lodgment, third-party withdrawal, debit card issuance and other e-channels. In other words, you are not choosing between yield and normal bank-account features quite as sharply as you would with a single-purpose app wallet. For readers who want one account that still looks and feels like banking, Fidelity is the most rounded traditional option in this shortlist.
5) GTInstant by Guaranty Trust Bank — best low-friction starter account
GTInstant is not trying to be the highest-yield, high-balance winner on this list. Its strength is access and speed: GTBank says the account number and Naira MasterCard are issued instantly, and you can open it with BVN or NIN. The published interest rate is 8.175%, which is respectable for an entry-level product, but the built-in limits tell you who it is really for.
The caps are strict. GTBank says the maximum single deposit is ₦50,000 per transaction, and the maximum cumulative account balance is ₦300,000. If you somehow sat right at that balance ceiling for a full year, 8.175% would imply about ₦24,525 in annual interest. That is fine for a starter saver, but the ceiling makes GTInstant a poor place to warehouse serious long-term savings.
There are other trade-offs too. The GTInstant Naira MasterCard is stated to be valid for local transactions only, which reduces its flexibility if you wanted broader card use. The good news is that the account can be upgraded to a higher-value account if you provide additional KYC documents. So GTInstant makes the most sense as a low-friction first step, a temporary holding account or a transaction-linked savings option — not as the best long-term home for large balances.
6) Jaiz Savings Account (Mudarabah) — best non-interest, Sharia-governed option
Jaiz is the clearest fit here if your priority is avoiding a fixed-interest structure altogether. The official account documents say the savings relationship is based on Mudarabah Mutlaqah, with the bank acting as Mudarib and the customer as Rabb-ul-Maal. Instead of promising a fixed advertised interest rate, the bank says profit is shared according to the prevailing Profit Sharing Ratio Schedule. That means you are not buying rate certainty in the way you are with Flex Naira, SafeLock or Fidelity.
There are still some concrete rules you should know. Profit for savings deposits is calculated monthly, and a customer forfeits profit if the average balance falls below the bank's investable Mudarabah savings threshold of ₦2,000 at any period in that month. Changes to the profit-sharing ratio are subject to approval of Jaiz's Advisory Committee of Experts (ACE). Separately, Jaiz's 2023 annual report says ACE validates products and services in line with Shari'ah principles, with decisions final subject to the CBN's Financial and Regulatory Advisory Committee of Experts (FRACE).
That governance point matters because it lets you distinguish this account from vague "ethical" marketing. In this research, Jaiz is not treated as Sharia-governed just because it is non-interest; it is treated that way because the source packet names the internal certifying body and the oversight chain. The trade-off is equally clear: because no fixed public return is provided here, you cannot responsibly forecast a naira outcome on ₦500,000 from this packet alone. Jaiz's digital onboarding page also says customers can begin opening the account online and receive an account number right away, which helps if you want the non-interest option without starting at a branch.
Ranking methodology
This list ranked products by use-case fit first, not by the biggest headline percentage alone. The criteria were:
Clarity and competitiveness of published returns
We gave more credit to products that clearly state the rate or profit mechanism in official materials. That is why Flex Naira's simple 12% p.a. scores well for clarity, while FairTarget's up to 20% p.a. is attractive but less fully explained in the cited page.
Liquidity and penalty structure
We looked at whether you can get your money when needed, and what happens if you do. A flexible account with a monthly interest penalty can still rank highly, but the penalty matters.
Barrier to start
Minimum balance, minimum lock amount, account caps and opening friction were all considered. Products like FairTarget and GTInstant do well on ease of entry for different reasons.
Strength of documented backing
We preferred products issued by named banks or backed by clear provider disclosure, but we only made explicit regulatory claims where those claims appeared in the source packet.
Distinct job-to-be-done
A shortlist is more useful when each pick fills a recognisable role: emergency savings, named goals, fixed-lock saving, bank-style saving, starter saving or non-interest saving.
A final note on transparency: rates and rules were taken from official sources reviewed on September 10, 2026 and can change. Where official pages conflicted — especially on SafeLock's top advertised rate — we surfaced the conflict rather than smoothing it over.
Entry blurb
- Flex Naira by PiggyVest: This ranks first because it is the best balance of access and published return for most readers. You get a clearly stated 12% p.a. and an everyday-flexible wallet, but only if you can keep your withdrawals disciplined enough not to lose that month's interest.
- FairTarget by FairMoney: FairTarget placed high because it solves a very practical Nigerian problem: saving separately for rent, school fees, travel and other big bills without fully locking your money away. Its mix of up to 20% p.a., no minimum balance, automatic plan saving and multiple goals is strong, even if the top-rate mechanics need clearer public explanation.
- SafeLock by PiggyVest: SafeLock earned its spot as the strongest high-discipline option in the sample. The exact top rate needs provider clarification because PiggyVest's public pages conflict, but even the more conservative 19.5% headline keeps it near the top for fixed savings.
- Fidelity High Yield Savings Account: Fidelity made the list because it is the best example here of a savings product that still functions like a regular bank account. The top published yield is lower than the app-based lock products, but the trade-off is more familiar banking utility.
- GTInstant by Guaranty Trust Bank: GTInstant is here for readers who value speed and low friction over maximum yield. Instant account and card issuance are useful, but the ₦300,000 balance cap limits how far this product can go as a serious savings home.
- Jaiz Savings Account (Mudarabah): Jaiz belongs on the shortlist because it is the clearest documented non-interest option in this research. It is not for rate certainty; it is for readers who want a profit-sharing structure with named Sharia governance rather than a fixed interest promise.
Comparison table
| Rank | Product | Best for | Published return / profit model | Access rules | Minimum / balance rule | Main catch |
|---|---|---|---|---|---|---|
| 1 | Flex Naira by PiggyVest | Emergency fund / best overall | 12% p.a. | Flexible withdrawals; can initiate only once every 10 hours; ₦3m+ withdrawals take 3 working hours | Minimum accessible amount ₦2,000 | More than 4 bank withdrawals or 6 Pocket withdrawals in a month means you lose that month's accrued interest |
| 2 | FairTarget by FairMoney | Named goals | Up to 20% p.a. | "Flexible access while saving" | No minimum balance; user-defined duration | Source cited here does not explain exactly what qualifies for the top rate |
| 3 | SafeLock by PiggyVest | Fixed, high-discipline saving | FAQ ladder from 14% to 21% p.a. prorated; landing page says up to 19.5% p.a. | No access until maturity; some locks can be broken after 90 days if interest is set for maturity, but accrued interest is forfeited | Minimum per lock ₦1,000; maximum ₦100m | PiggyVest's own public pages conflict on the top rate |
| 4 | Fidelity High Yield Savings Account | Traditional bank-style saving | Tiered: 7.95%, 8.45%, 9.45%, 10.45% p.a. by balance band | Accessible bank account; interest paid monthly | Open with any amount; minimum operating balance ₦5,000 | No interest if you make more than 3 withdrawals in a month |
| 5 | GTInstant by GTBank | Starter account | 8.175% | Instant account and local-only Naira card | Max single deposit ₦50,000; max cumulative balance ₦300,000 | Balance cap makes it unsuitable for larger savings |
| 6 | Jaiz Savings Account (Mudarabah) | Non-interest / Sharia-governed saving | Profit-sharing under Mudarabah; no fixed advertised rate in this packet | Savings profit calculated monthly | Profit forfeited if average balance falls below ₦2,000 threshold during the month | No fixed return means less yield certainty for planning |
Bottom line
If you want the single strongest first pick from this list, start with Flex Naira by PiggyVest. It is not the highest headline return here, but it is the best blend of clear pricing, practical access and low confusion. A published 12% p.a. on a flexible wallet is easy to understand, and the trade-off — staying under the withdrawal limits if you want to keep your monthly interest — is at least visible and manageable.
That said, the right runner-up depends entirely on your job for the money. Pick FairTarget if you are saving toward named bills and want structure without a full lock. Pick SafeLock if discipline matters more than flexibility and you are comfortable verifying the current top rate directly because PiggyVest's public pages are not aligned. Pick Fidelity HYSA if you want a bank-style account, GTInstant if you want a frictionless starter product, and Jaiz if your first filter is a documented Sharia-governed non-interest structure rather than a fixed return.
FAQ
Frequently Asked Questions
Which account in this list has the highest published return?
Which option is best for emergency savings?
Can I lose interest even if the account allows withdrawals?
Is there a proper non-interest or Sharia-governed option here?
Which product is easiest to start with small money?
Before you open anything, decide the job first: emergency money, a named future bill, a hard lock, a normal bank savings account, a starter account or a non-interest structure. Then check the provider's current official page again before funding it, especially where the return is quoted as "up to" or where public pages already show a conflict. That small extra step can save you from opening the right product for the wrong reason.
Sources
- Jaiz Omni Channel(official_site)
- GTInstant | GTBank(official_site)
- Fidelity High Yield Savings Account - Fidelity Bank Plc(official_site)
- FAQs - PiggyVest(official_site)
- Flexible Savings with Flex Naira™ - PiggyVest(official_site)
- Savings - Earn up to 20% p.a. | FairMoney(official_site)
- JAIZ BANK PLC(official_site)
- RC: 476637 Instant Banking Download JaizMobilePlu(official_site)
- Lock funds with Safelock™ - PiggyVest(official_site)